Water Leak Insurance Claims: Process & Pitfalls
Water leak insurance claims: what's covered, how to document damage, the denial traps to avoid, and how to negotiate a fair payout. A 2026 US homeowner's guide.
10 MIN READ · UPDATED 2026-09-23
Key takeaways
- Standard policies cover sudden, accidental water discharge — not gradual leaks, wear and tear, or flood (which needs separate coverage).
- Document before you clean up: timestamped photos and video, the failed part kept as evidence, and a room-by-room inventory.
- You have a contractual duty to mitigate — shut off water and dry out fast, and keep every receipt for reimbursement.
- Denials can be appealed with a plumber's written cause-of-loss opinion and written citations of policy language; never misrepresent facts.
- Run the deductible math before filing small claims, and add a sewer-backup rider plus leak detection to prevent the next loss.
A single failed washing-machine hose can release hundreds of gallons of water in an hour and leave you staring at $20,000–$50,000 in damage — and your insurer's first question will be whether the leak was sudden or something that had been dripping for months. Water damage is among the most common homeowners insurance claims in the US, and also among the most frequently disputed, because policies draw a sharp line between sudden accidents and slow deterioration. Get the documentation and the language right, and a claim flows; get it wrong, and a legitimate loss can be denied on a technicality. This guide walks through the claims process step by step, the pitfalls that sink claims, and the decisions — like whether to file at all — that protect both your home and your coverage.
Sudden vs. Gradual: The Coverage Line That Decides Everything
Nearly every standard HO-3 homeowners policy covers sudden and accidental discharge of water from plumbing, appliances, and HVAC systems. A burst supply line, a failed water-heater tank, a dishwasher hose that lets go overnight — these are textbook covered events. But the same policy excludes damage from gradual leaks and seepage, wear and tear, neglect, and faulty workmanship. A pinhole leak that has been dripping inside a wall cavity for two years, slowly rotting studs and subfloor, will be denied even though the homeowner only discovered it yesterday.
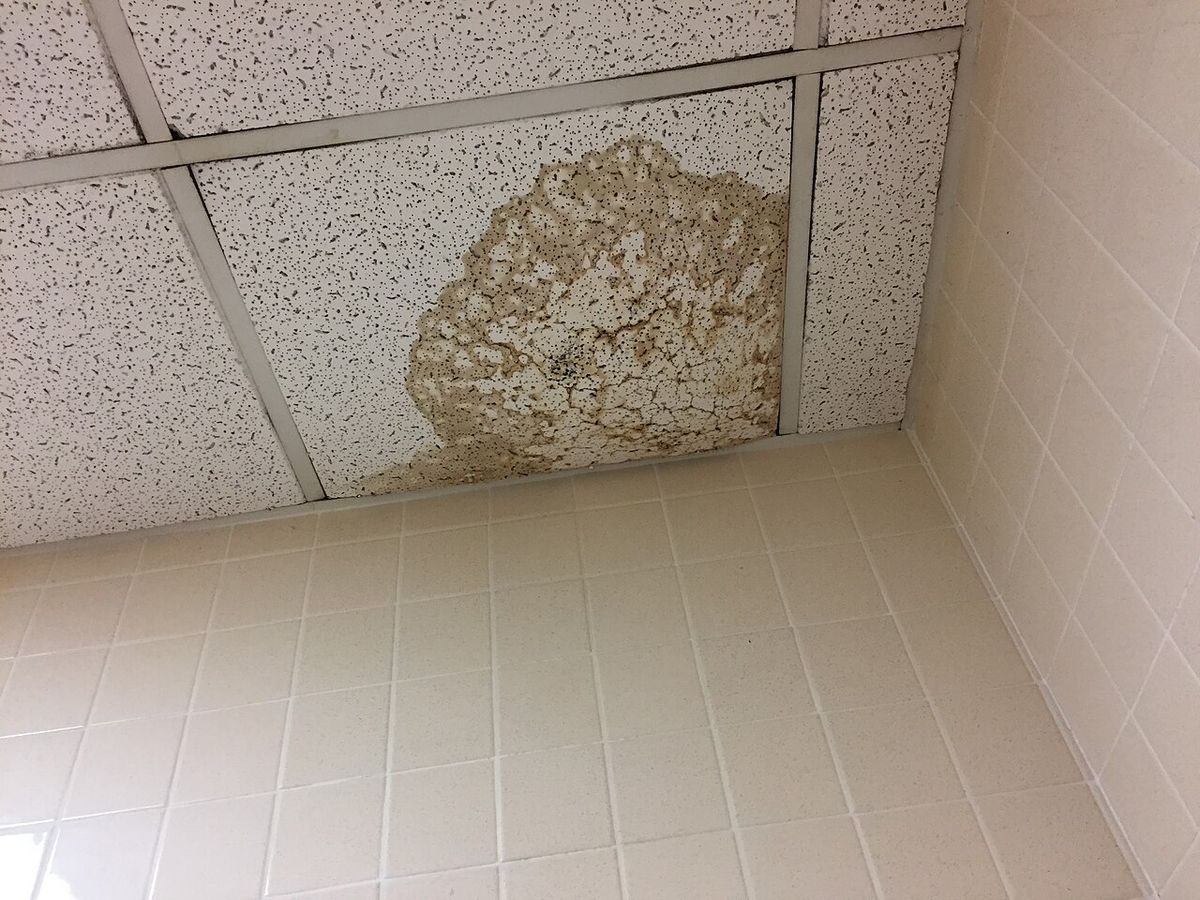
This distinction is where most disputes live. Insurers look for evidence of duration: water staining patterns, mold growth that takes weeks to develop, corrosion buildup on fittings, and moisture-meter readings in surrounding materials. An adjuster who finds heavy staining and old mold behind a vanity has a plausible case that the leak predated the policy period or was knowable. That is why a licensed plumber's written cause-of-loss opinion — stating when the failure likely occurred and why — is one of the most valuable documents in a water claim.
Two more boundaries matter. First, flood is not water damage: rising groundwater, storm surge, and surface water running into the house require separate flood insurance; your homeowners policy will not touch them. Second, mold is usually sublimited: many policies cap mold remediation at $1,000–$10,000 unless you bought additional coverage. And remember the resulting damage doctrine — the failed pipe or worn-out hose itself is generally not covered, but the damage the water did to floors, walls, and belongings is. Knowing these lines before you call your insurer shapes every conversation that follows. If any of this feels ambiguous, ask your agent to walk through the water-damage exclusions on a live call and summarize the answers in an email you can keep.
The First 48 Hours: Document Before You Dry
What you do in the first two days determines the ceiling of your settlement. Start by stopping the source: shut off the local valve or the main, and call a plumber for an emergency repair. An after-hours service call typically runs $200–$500, and that receipt becomes part of your claim. Then, before any cleanup begins, document everything — this is the single most common piece of advice claims professionals give, and the most commonly ignored.
Shoot video first, narrating as you walk the damage: wide shots of each room, then close-ups of the failed component, water lines on walls, warped flooring, and damaged contents. Take still photos with timestamps enabled. Photograph the failed part itself — the burst hose, the cracked fitting, the corroded connector — and keep the failed parts in a bag rather than throwing them away; they are physical evidence of the cause of loss. Note the date and time you discovered the leak and when you shut the water off.
Build a room-by-room inventory of damaged contents with approximate ages, purchase prices, and replacement costs. Credit-card and bank statements can reconstruct purchases when receipts are gone. Call your insurer promptly — policies require prompt notice, and delayed reporting is a legitimate denial reason — and get a claim number, your adjuster's name, and a direct phone number in writing. Keep a claim journal from day one: every call, every name, every promise, dated. Insurers track their file notes; you should track yours. Keep copies of everything you send the insurer, because claim files do get misplaced.
Why Claims Get Denied — and How to Push Back
The most common denial reasons are worth memorizing, because each has a counter. Long-term or gradual damage is the biggest: if the insurer concludes the leak ran for weeks or months, coverage evaporates. Counter it with the plumber's cause-of-loss opinion, photos showing the failure was sudden (a burst line looks different from a weeping joint), and your own maintenance records. Maintenance neglect — corroded supply lines, a 20-year-old water heater that was never serviced — invites the wear-and-tear exclusion; regular service records are your defense.
Other frequent denials: the flood exclusion applied to groundwater or storm water entering the home; late notice, where the homeowner waited weeks to report; and policy-specific exclusions like water or sump-pump backup, which many base policies exclude entirely unless you bought the endorsement. Read your policy's exclusions section — not the marketing summary, the actual contract — before accepting a denial at face value.
If you are denied, demand the denial in writing with the specific policy language cited. Adjusters sometimes reverse course when asked to put the reasoning on paper. File a formal appeal through the insurer's process, and supplement the file with an independent contractor's estimate and the plumber's opinion. For large or stubborn claims, a public adjuster — licensed to represent you, typically for around 10% of the settlement — can be worth it. As a last resort, your state's department of insurance takes consumer complaints and audits claim-handling practices. One hard rule: never embellish or misrepresent anything. Material misrepresentation can void the entire policy, and insurers share fraud data. A calm, paper-backed appeal beats an angry phone call every time.
Your Duty to Mitigate Is Not Optional
Buried in every homeowners policy is a duty to mitigate: you must take reasonable steps to prevent further damage after a loss. This is not courtesy — it is a coverage condition. Shut off the water, move undamaged belongings out of the wet area, and get professional water extraction and structural drying underway quickly. Professional dry-out for a moderate loss typically runs $1,500–$5,000; a severe whole-house event can reach $10,000 or more. Keep every receipt: reasonable mitigation costs are generally reimbursable under the policy.
Speed matters because water damage compounds. Drywall wicks moisture upward, subfloors swell, and mold can begin colonizing damp materials within 24–48 hours in warm conditions. If you wait a week to call a restoration company and mold blooms across the basement, the insurer can credibly argue the secondary damage is your fault — and they will. Document your mitigation steps in the claim journal with dates: when the plumber arrived, when extraction started, when dehumidifiers were placed.
For larger losses, hire a licensed restoration contractor rather than renting fans yourself; insurers take professional moisture-mapping and drying logs seriously, and those logs become evidence that you did your part. Do not authorize demolition beyond what is needed to dry the structure until the adjuster has seen the damage, or at least until you have thorough photo and video documentation. And do not sign any assignment-of-benefits paperwork from a contractor without understanding it — some versions hand your claim rights to the contractor. When in doubt, have your own licensed contractor — not the insurer’s preferred vendor — scope the work.
Adjusters, Estimates, and Getting Paid Fairly
You will deal with one of three adjusters. A staff adjuster works for your insurer. An independent adjuster is a contractor hired by the insurer — they work the insurer's file, not yours. A public adjuster is hired and paid by you. Knowing who sits across the table keeps expectations realistic: the first two are not your advocates, though most handle files professionally.
Get two or three written estimates from licensed contractors before the adjuster finalizes the scope. Restoration pricing software like Xactimate sets line-item prices insurers respect, so estimates built on that basis carry weight. Understand how you are paid: many policies pay actual cash value (ACV) first — replacement cost minus depreciation — and release the recoverable depreciation after you complete repairs and submit invoices. That two-check structure surprises homeowners who expect one lump sum.
When hidden damage surfaces mid-repair — rotted subfloor under the tile, mold inside the wall cavity — your contractor files a supplement with the insurer, with photos and line items. This is routine in water losses; do not let a contractor eat the cost silently or cut corners. Review the adjuster's scope line by line against your contractor's estimate, question anything missing (baseboards, paint blending, dehumidifier rental days), and do not sign a final release until repairs are complete and you are satisfied. For contents, a detailed inventory with photos and proof of purchase is what turns a lowballed offer into a fair one. Patience and paperwork win more settlements than pressure tactics ever will.
Prevention, Riders, and Whether to File at All
Before you file, do the deductible math. If the damage is $6,000 and your deductible is $2,500, the net recovery is $3,500 — worth weighing against the cost of a claim on your record. A single water claim can raise premiums at renewal, and two or three claims within a few years can trigger non-renewal in some markets. Many experienced homeowners self-pay losses near the deductible and reserve claims for the five-figure events insurance is designed for. There is no universal right answer; there is only your deductible, your claim history, and your state's market.
Review your policy's endorsements before the next loss, not after. A water/sewer backup rider — covering sump-pump failures and drain backups the base policy excludes — typically costs $40–$100 per year and is one of the best values in homeowners insurance. Consider raising a low mold sublimit, and if you have a well, look at equipment-breakdown coverage for the pump. Ask your agent to walk the exclusions page with you once a year; fifteen minutes of review beats a surprise denial.
On the prevention side, the upgrades that matter most are cheap relative to a claim. Smart leak detectors with automatic shutoff valves run $500–$2,500 installed and can stop a burst-line disaster while you are at work. Replace rubber washing-machine hoses with braided stainless steel, swap a water heater approaching the end of its 8–12-year life before it fails, and make sure everyone in the house knows where the main shutoff is — and that it actually turns. Costs are 2026 US market ranges; get itemized local quotes, and use licensed plumbers for any supply-line or valve work. Revisit this checklist every couple of years as plumbing ages and policy language evolves.
Frequently asked questions
Generally no — gradual damage from a long-running leak is excluded under most HO-3 policies, even if you only just discovered it. What is covered is sudden, accidental discharge, like a supply line that bursts. If you find an old leak, document it, call a plumber for a cause-of-loss opinion, and talk to your agent before assuming either way.
Mold resulting from a covered water loss is typically covered up to your policy's mold sublimit, commonly $1,000–$10,000 unless you bought higher limits. Prompt professional dry-out is essential — mold that grows because mitigation was delayed can be excluded as a failure of your duty to mitigate. Check your declarations page for the exact sublimit.
It can. A single water claim often leads to a modest increase at renewal, and multiple claims within a few years can make non-renewal more likely in some markets. That is why many homeowners self-pay losses close to the deductible and reserve claims for major events. Review your claim history and deductible before deciding.
No, and the distinction is critical. Flood — rising groundwater, storm surge, surface water flowing into the home — is excluded from standard homeowners policies and requires separate flood insurance. A burst pipe, failed appliance hose, or leaking water heater is 'water damage' and falls under your homeowners coverage, subject to the sudden-vs.-gradual rule.
File with your own insurer first and let subrogation sort out liability — your policy pays you, then pursues the responsible party. In condos, the building master policy and your HO-6 policy split responsibility at defined boundaries, so notify the HOA or management in writing immediately and photograph everything. Keep all correspondence.
For large or disputed claims, a licensed public adjuster can be worth their fee — typically around 10% of the settlement — because they document, scope, and negotiate on your behalf. For straightforward smaller claims, most homeowners do fine working directly with the insurer's adjuster plus a licensed contractor's estimate. Get the fee agreement in writing before signing.